EU Motor Vehicle · Whitepaper
Back to Resilient Margins
How Europe’s motor vehicle original equipment manufacturers (OEMs) and suppliers can outperform in a persistently turbulent market. Structural cost inflation, margin erosion, and new competitors are resetting the economics of the region. This paper lays out a structured path to close the profit and loss (P&L) gap.
Download the white paper
Inside the report:
Where European margins are eroding and why
The cost levers that close the P&L gap
A six-week diagnostic and implementation roadmap
Europe faces structural cost inflation, margin erosion, and competitive pressure, making a cost-reduction program essential to close profit and loss (P&L) gaps.
Value is shifting toward batteries, electronics, and software, where Europe has higher structural costs and greater dependency. At the same time, global competitors are resetting price points in the region.
Rebuilding competitiveness requires strategic focus, structural adaptation, and execution. Near-term cost reduction is the quick win that creates the foundation.
The value shift favorslower-cost regions
Value in the vehicle is moving toward batteries, and Europe pays the most for them. European battery packs cost 56 percent more than Chinese packs.
China’s vertically integrated model compresses battery, software, and industrialization cycles. Challengers are now localizing high-value activities inside Europe, bringing that cost advantage with them.
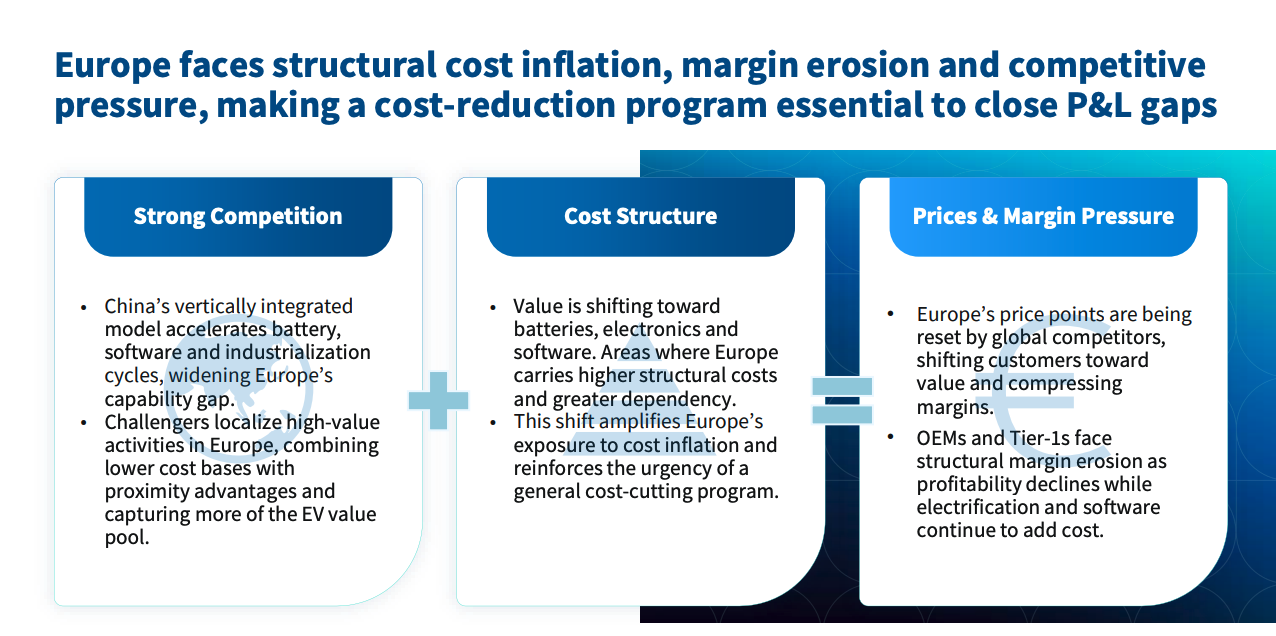
Three pressures are compressing European margins
The competitive gap is no longer only about product
Earnings before interest, taxes, depreciation, and amortization (EBITDA) margins across major European OEMs, commercial vehicle OEMs, and Tier-1 suppliers have deteriorated since 2021. The gap now comes down to cost architecture, agility, and integration.
Costs have outpaced what customers will pay
Producer prices for machinery and motor vehicles have risen 26 to 32 percent since 2015. European consumers can no longer afford an expensive “Made in Europe,” and Chinese OEMs are pricing closer to willingness to pay.
Cost reduction is the foundation, not the endpoint
Near-term cost reduction is a quick win that creates the foundation for the broader agenda. A structured program links total cost and margin levers, workflow improvement, and each cost center to clear fields of action.
The competitive gap is no longer only about product.
Back to Resilient Margins, Ducker CarlisleSee the full six-week methodology
The white paper details the cost structure diagnostic, the action levers rated against industry maturity, and the quarterly implementation roadmap that prioritizes quick wins.
Download the ReportTurn cost pressure into durable margin
Get the full analysis of Europe’s motor vehicle cost structure and the structured program to close the P&L gap.
Prefer to talk it through? Book a Briefing with our Motor Vehicle Europe team.